Seller Net Sheet (2026): Every Line, and a Working Calculator
Sep 16, 2026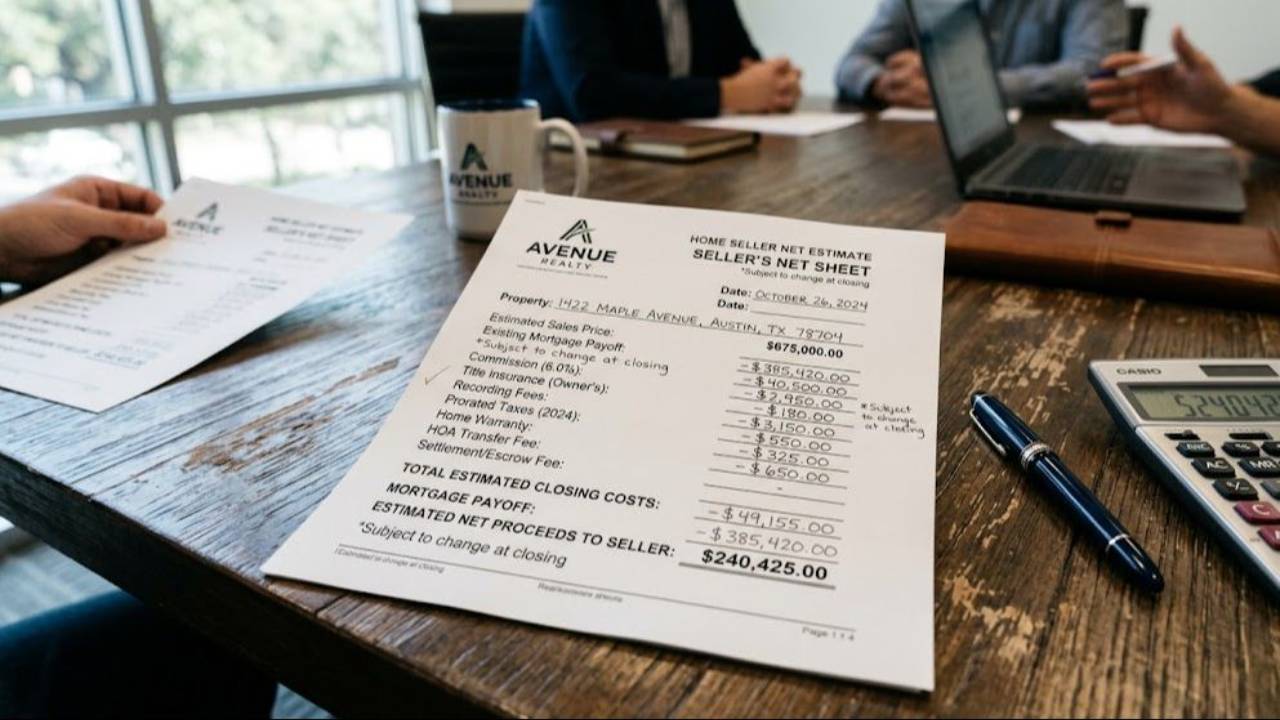
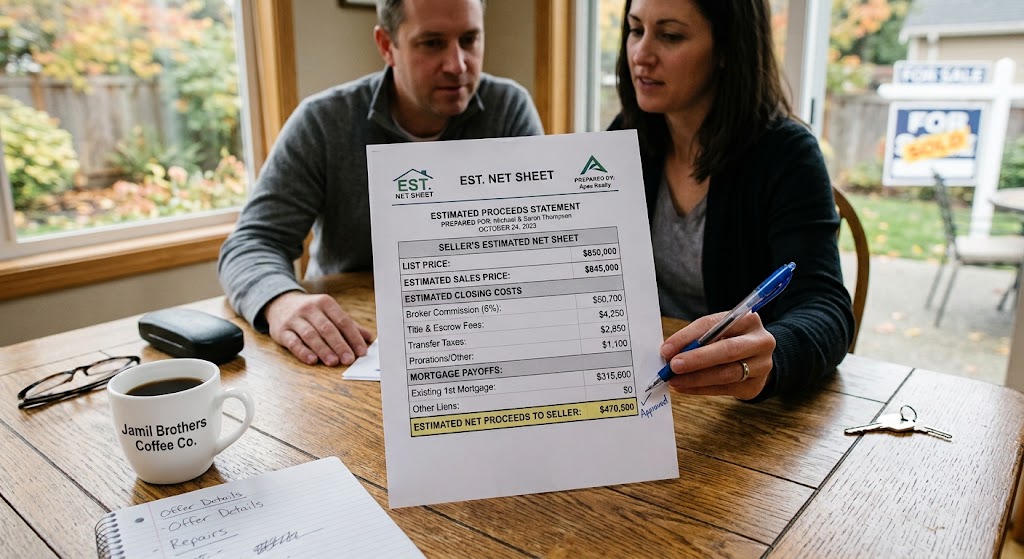
Search for a seller net sheet and you get calculators. Page one is almost entirely title companies, each built for a single state. None explains what belongs on the sheet, where the numbers come from, or which lines get left off. That is the part that costs you a listing.
This is the working version: every line, who customarily pays it, how variable it is, and a calculator you can use on a real file. If you are weighing real estate coaching, knowing this cold is the cheapest credibility you will buy. A seller who understands their own number stops hesitating.
A net sheet is an estimate you prepare, not a settlement document anyone is bound by. I am a Realtor, not a lawyer, a CPA or a settlement agent. Figures below are cited to statute or to the agency that publishes them, with the date I read them. The rates are jurisdiction specific and several of them change by county, so the sheet you hand a seller should be built on quotes from your settlement agent, not on a national average.
- A net sheet is an estimate, not a settlement statement. It is not a Closing Disclosure and not an ALTA statement, and it binds nobody.
- Payoff is not balance. It adds per diem interest to the closing date plus statement, wire and release recording fees. The balance understates the deduction every time.
- Buyer-broker compensation is its own line now. Burying it inside one commission percentage reproduces the assumption the litigation was about.
- Compensation and concession are the same money to your seller, not to the buyer's loan. A generic concession eats the buyer's interested-party contribution headroom. Compensation generally did not, under April 2024 agency guidance.
- The transfer tax is local, not national. Northern Virginia sellers pay three times what the rest of Virginia pays, and crossing the DC $400,000 line adds $1,411 of tax against $1,000 of price.
- Give a range and date the sheet. An undated single number is a promise you did not mean to make.
- What a net sheet is, and the three documents it is not
- Every line that sits between price and proceeds
- Your payoff is not your balance
- Where buyer-broker compensation goes now
- Build the sheet
- Transfer taxes, and why the number is local
- The association lines agents forget
- Prorations run in both directions
- Sellers who do not live in the state
- Nine mistakes that show up on real net sheets
- How to present it without creating a problem
- What this guide does not cover
- Frequently asked questions
What a net sheet is, and the three documents it is not
Start with the useful negative. I could find no statute defining a seller net sheet, prescribing its contents, or restricting who may prepare one, and the definitions online are mostly marketing copy from companies selling calculators. Not a reason to avoid one. A reason to be precise about what you hand over.
A net sheet is your good faith estimate of what the seller walks away with, prepared before there is a contract, from numbers that are mostly quotes and partly assumptions. Three real documents get confused with it.
| Document | Who produces it | When | What it binds |
|---|---|---|---|
| Your net sheet | You | Before listing, or when an offer arrives | Nothing. It is an estimate |
| Closing Disclosure | The lender, through the settlement agent | At least three business days before consummation | A federal form under Regulation Z, with tolerance rules |
| ALTA Settlement Statement | The settlement agent | At closing | An industry form. ALTA itself says it is not meant to replace the Closing Disclosure |
| Estimate of proceeds | The title or settlement company | On request | Nothing, but it comes from the party who will actually disburse |
Closing Disclosure requirements at 12 CFR sections 1026.19(f) and 1026.38; ALTA's own description of its settlement statement forms. Read 16 September 2026.
I found no authority treating a net sheet as unauthorised practice of law. The live rules are your state's misrepresentation and disclosure provisions: Virginia's 18VAC135-20-300, Maryland's Business Occupations and Professions section 17-322. Neither mentions net sheets. Their outright misrepresentation prongs require knowing or wilful conduct, but both also carry disclosure duties keyed to ordinary care, so a careless estimate is not outside them. The protection is what makes the sheet useful anyway: show the lines, show the sources, date it, and give a range.
Every line that sits between price and proceeds
The whole stack. Variability is the column most articles skip and the one telling you where to stop guessing.
| Line | Customarily paid by | How variable |
|---|---|---|
| Mortgage payoff, with per diem and lender fees | Seller | Low once quoted, high if estimated |
| Second lien or HELOC payoff | Seller | Low once quoted |
| Listing-side brokerage fee | Seller | Negotiated, no standard |
| Buyer-broker compensation | Negotiated. Seller funded or not | High |
| Transfer, grantor or documentary tax | Varies by state, often seller | High between states, sometimes counties |
| Recordation tax | Usually buyer, split in some states | High |
| Owner's title policy | Buyer in Virginia, Maryland and West Virginia. County by county in Florida | High |
| Settlement or escrow fee | Often split | Medium |
| Attorney fee | Seller, in attorney states | Medium |
| Association resale packet | Seller, by statute in several states | Low, often capped |
| Special assessments outstanding | Seller | High |
| Property tax proration | Either direction | High |
| Association dues proration | Either direction | Medium |
| Concession toward buyer costs | Seller | Negotiated |
| Repair credits after inspection | Seller | Unknown at listing |
| Home warranty | Negotiated | Medium |
| Release recording and payoff wire fees | Seller | Low |
| Unpaid water or municipal escrow | Seller | Low |
| Judgments and liens of record | Seller | Unknown until title work |
| Nonresident or FIRPTA withholding | Seller | Binary. It applies or it does not |
Four go missing most often: the association packet, an outstanding special assessment, the payoff fees, and whichever direction the tax proration runs. Each is small enough to feel ignorable and large enough to be why the seller calls you the day before closing.
Your payoff is not your balance
The largest deduction on almost every sheet, and the one most often wrong. The seller reads the balance off their app and you write it down. That is not what the lender will demand.
A payoff statement is the lender's binding figure through a stated date. It contains:
- Unpaid principal balance. The number on the app.
- Interest accrued to the payoff date. Residential mortgages are paid in arrears, so interest runs daily from the last paid instalment. Per diem is principal times note rate divided by 365, though some notes use 360.
- A payoff statement or demand fee, and a wire fee. Servicers publish these, state by state. One national servicer's Florida schedule, revised July 2025, shows up to $30 for the payoff quote and up to $25 for the wire. Pull your servicer's own schedule.
- The release recording fee. Satisfying the deed of trust has to be recorded, and the clerk charges for it.
- Anything the servicer has capitalised. Escrow shortage, force placed insurance, late charges.
Take a $400,000 balance at 6.5 percent. Per diem is about $71. A thirty day escrow adds roughly $2,137 of interest before you count a single fee. Put the balance on the sheet instead of the payoff and you have understated the seller's largest deduction by well over two thousand dollars, in the direction that disappoints them.
Order the payoff. Under Regulation Z a servicer must provide an accurate payoff statement within a reasonable time and no more than seven business days after a written request, with exceptions including bankruptcy and foreclosure. Watch the good through date: a payoff that expires before your closing is not a payoff.
12 CFR section 1026.36(c)(3); Fairfax Circuit Court land records fee schedule CCR A-50 effective 1 July 2026 for the release recording cost; a national servicer's published fee schedule revised July 2025. Read 16 September 2026.
The HELOC has to be closed, not zeroed
A second deed of trust pays off like a first. A home equity line does not. Paid only to zero, the lender need not release it and the seller can draw again before recording, so settlement agents require a written close out request alongside the demand. Standard practice rather than statute, and the sort of thing that delays a closing a week when nobody asks early.
Where buyer-broker compensation goes now
The practice changes took effect on 17 August 2024. What agents still get wrong is not the rule but the consequence of how you write the line.
What actually changed, and what did not
| What agents say | What is true |
|---|---|
| Sellers cannot pay the buyer's agent any more | False. Sellers may still offer compensation off the MLS, and may offer concessions on the MLS |
| Compensation cannot be advertised anywhere | False. It cannot appear on the MLS. Flyers, emails, signs and brokerage websites are permitted |
| Commissions were capped or standardised | False. The mandated language says the opposite, that fees are not set by law and are fully negotiable |
| Concessions simply replaced compensation | Partly false. They are distinct instruments, and a concession cannot be conditioned on or tied to payment to a buyer broker |
| The settlement was thrown out | False. The Eighth Circuit affirmed approval on 19 August 2026 |
NAR Summary of 2024 MLS Changes; NAR settlement FAQs; NAR guidance on compensation, commission and concessions dated 13 August 2024; NAR reporting on the Eighth Circuit decision of 19 August 2026. Read 16 September 2026. Rehearing petitions filed at the start of September 2026 were still undecided on 16 September 2026, and several related cases remain stayed until the appellate mandate issues. The practice changes are settled; the litigation is not over.
Two requirements matter to your sheet. Offers of compensation cannot be published on an MLS, and you need the seller's prior approval before one is made or paid. Both point the same way: the number belongs on its own line, agreed with your seller.
The part almost nobody tells agents
Seller funded buyer-broker compensation can be structured two ways. The seller nets the same either way. The buyer's loan does not.
In April 2024 FHA said that where sellers continue to pay buyer-side commissions as a matter of state or local custom, and the amounts are reasonable, existing policy would not treat those payments as interested party contributions. Fannie Mae and Freddie Mac confirmed the same position on 15 April 2024, conditioned on the payment remaining customary by local convention. Written as a generic concession instead, the same dollars consume the buyer's interested party contribution capacity, which is capped at 3 percent above 90 percent loan to value on a conventional principal residence. On a high loan to value deal that difference can break the financing.
FHA guidance of April 2024 as reported by a state Realtor association; NAR Washington Report on the FHFA confirmation of GSE guidance, 15 April 2024; Fannie Mae Selling Guide B3-4.1-02, updated 7 May 2025. Read 16 September 2026. The agency carve out is conditioned on the payment being customary by local convention, and after two years of negotiated fees that condition is a live question. Confirm the current position with the buyer's lender rather than relying on this paragraph.
Give buyer-broker compensation its own line, label it negotiated rather than fixed, and note which instrument you are modelling. When the objection comes, work from the commission objection handlers. What you should not do is print 5 percent on one line and let the seller assume the split is settled.
Build the sheet
Jurisdiction comes first because it sets the one rate this can prefill. Every field with no defensible national figure loads empty, brokerage included, because a prefilled commission is the assumption this article argues against.
Only the transfer tax rate prefills, and the price loads at an illustrative $750,000. The rate is 0.30 percent for the Northern Virginia localities charging the grantor tax plus both regional fees, 0.10 percent elsewhere in Virginia, 1.1 percent in DC below $400,000 and 1.45 percent at or above it, and the low end of the West Virginia range. Maryland prefills 0.25 percent, the customary seller half of the state tax rather than a statutory allocation, with county transfer tax extra. Somewhere else prefills zero, a placeholder and not a rate. Everything else starts empty on purpose. Costs and payoff excludes prorations, which apply separately and are signed. There is no withholding line, no owner policy toggle and no attorney fee line. Modelling the buyer broker figure as a concession models a general concession the buyer may put toward their own broker; a concession tied to that payment is not permitted. An estimate for planning, not a settlement statement.
Switch from Northern Virginia to DC on the same $750,000 and the transfer tax goes from $2,250 to $10,875. That is why a national net sheet calculator cannot be trusted without knowing where the house is, and why this one refuses to invent lines it cannot know.
Transfer taxes, and why the number is local
The line that makes national calculators useless. Rate, payer and sometimes structure change at a state line and occasionally a county line. The four I am licensed in, from statute.
| Virginia | District of Columbia | Maryland | West Virginia | |
|---|---|---|---|---|
| Seller transfer or grantor tax | 0.10 percent statewide. 0.30 percent in the Northern Virginia localities, which add the WMATA and congestion relief fees | 1.1 percent, rising to 1.45 percent at $400,000 and above | 0.5 percent state, customarily split, so 0.25 percent to the seller. County tax on top | 0.33 to 0.55 percent, state plus county |
| Statutory payer | Grantor, sections 58.1-802, 802.3 and 802.4 | Transferor, section 47-903 | By agreement, with one exception below | Grantor, section 11-22-2 |
| Owner's title policy | Buyer by convention | Not verified for this guide | Buyer by convention | Buyer by convention |
| Closing model | Settlement agent, attorney prepares documents | Settlement agent or attorney | Title producer if insured | Attorney required |
Va. Code sections 58.1-802, 58.1-802.3, 58.1-802.4; D.C. Code section 47-903; Md. Tax-Property section 13-203; W.Va. Code section 11-22-2. All read 16 September 2026. Statutory payer is the default rather than a prohibition: Virginia lets the parties arrange for the grantee to pay, West Virginia shifts the tax to a grantee who accepts the deed unpaid, and DC makes the transferee jointly liable on the transferor's default. The owner's policy conventions come from underwriter practice guides and are convention, not law.
Three things in that table cost real money
- Northern Virginia sellers pay triple. On a $750,000 sale, $2,250 against $750 in Richmond. Same state, three times the tax.
- The DC cliff is not marginal. At $400,000 the rate applies to the entire amount, not the part above the threshold. A $399,000 sale carries about $4,389 of seller transfer tax. A $400,000 sale carries $5,800. That last thousand dollars of price costs your seller about $1,411.
- Maryland stops being negotiable for a first time buyer. On improved residential property bought by a qualifying Maryland first time homebuyer who will occupy it, the state rate halves to 0.25 percent and the whole of it moves to the seller by statute. The seller's cost is 0.25 percent either way, so the state tax is a wash. What changes is that the split is no longer yours to negotiate.
And two states that break the pattern completely
Florida charges documentary stamps at 70 cents per $100, Miami-Dade charges a different rate, and who pays the owner's policy varies by county within the state. If one state cannot agree with itself, a national average is fiction.
California looks cheap and is not. The county base is $1.10 per $1,000. Then the cities pile on: Los Angeles under Measure ULA reaches 4.45 percent between $5.3 million and $10.6 million and 5.95 percent above, and San Francisco tops out at 6 percent above $25 million. A California seller's transfer tax can be fifty times higher one block across a city line.
Fla. Stat. section 201.02; California City Finance documentary and property transfer tax rates effective 1 December 2025. Read 16 September 2026.
The association lines agents forget
Two seller costs, routinely absent until the settlement agent raises them.
The resale packet
In Virginia the resale certificate is the seller's cost by statute, and the Common Interest Community Board caps what the association may charge. Maryland caps its resale package fee too. DC allocates neither. These adjust, so quote the current figure.
Va. Code section 55.1-2316; the Virginia Common Interest Community Board publishes the maximum allowable fees separately. Read 16 September 2026. No dollar figure here, because the schedule adjusts and I could not confirm the current one.
Virginia splits this by property type. For a condominium, section 55.1-1966 gives the association a lien on the unit ahead of almost everything except real estate taxes, liens recorded before the declaration and sums unpaid on a first deed of trust, and requires a recordable statement of what is owed within ten days of a written request for a fee not exceeding $10, failing which the lien is extinguished as to that unit. For a lot in a property owners association, section 55.1-1833 governs instead, with neither that fee cap nor that extinguishment rule. Either way, a levied and unpaid special assessment is generally the seller's at closing.
Va. Code section 55.1-1966 (Condominium Act) and section 55.1-1833 (Property Owners' Association Act), read 16 September 2026.
Prorations run in both directions
The most misunderstood line on the sheet, and the one where a wrong sign moves the number twice as far as a missing line would. Direction depends on the billing cycle, not on any general rule.
| Situation | Direction | Effect on the sheet |
|---|---|---|
| Taxes billed in advance and paid | Buyer reimburses the seller for the unused part | Adds to proceeds |
| Taxes billed in arrears and not yet paid | Seller credits the buyer for the elapsed part | Subtracts from proceeds |
| Association dues, usually billed in advance | Buyer reimburses the seller | Adds to proceeds |
| A levied special assessment not fully paid | Seller pays the balance | Subtracts |
One sheet can carry a tax proration and a dues proration with opposite signs. Virginia runs a calendar tax year, with Fairfax instalments on 28 July and 5 December. Maryland runs a fiscal year from 1 July. Florida bills a year in arrears, the opposite direction from an advance payment market.
Ask the settlement agent what period the current bill covers, and whether it has been paid. Those two answers set the direction. Do not infer it from the state, or from the last deal in a different county, and do not leave the line at zero because you are unsure. A zero claims the proration is nil, which is almost never true.
Fairfax County Tax Administration billing dates; underwriter practice guides for Virginia, West Virginia and Florida tax cycles. Read 16 September 2026. The Maryland advance payment pattern is practitioner convention; I could not reach a state level source confirming it.
Sellers who do not live in the state
Binary. Either it applies and it is large, or it does not apply. Watch the base, because the three regimes do not share one. FIRPTA takes 15 percent of the amount realised, which is essentially the price. Maryland and West Virginia withhold on the total payment, meaning the price less the secured debt paid off at settlement and less the seller's disclosed selling expenses. Put the wrong base under the rate and you will be out by tens of thousands.
| Situation | Withholding | Note |
|---|---|---|
| Maryland nonresident individual | 8.75 percent | Of the seller's share of the total payment, which is net of secured debt and selling expenses |
| Maryland nonresident entity | 8.25 percent | Same base |
| West Virginia nonresident | 2.5 percent of the payment | An alternative of 4.58 percent of gain exists, and a principal residence exemption |
| Foreign person, anywhere in the US | 15 percent under FIRPTA | No withholding where the buyer acquires it as their own residence and the amount realised is $300,000 or less. The buyer is the withholding agent |
| Virginia or DC nonresident | None found | I could not find a nonresident real property withholding regime in either |
Maryland Form MW506NRS and the West Virginia nonresident withholding guidance, both of which compute total payment net of secured debt and disclosed selling expenses; the FIRPTA withholding rules and the residence exception. Read 16 September 2026. The Virginia and DC entries are negative findings from searching, not a confirmed absence.
Its own line, because a Maryland seller living in another state loses 8.75 percent of the payment at the table and needs to know before pricing. Do not compute the reduced FIRPTA band between $300,000 and $1 million yourself, and do not advise on whether an exemption or a reduced withholding certificate applies. That is a tax professional's call.
Nine mistakes that show up on real net sheets
Which is most common is practitioner judgement, not a researched finding. That each is an error is not.
- Using the balance instead of the payoff. Always wrong in the direction that disappoints the seller.
- Leaving out per diem interest. Even agents who order the payoff forget that a later closing date moves it.
- Forgetting the association resale packet. A seller cost by statute in several states, invisible until it is ordered.
- Assuming prorations run one way. The sign follows the billing cycle, not the state.
- Treating a concession as a price reduction. The most consequential item here, and the one below.
- Omitting unpaid assessments. They are a lien, collected at the table whether or not your sheet anticipated them.
- Assuming the buyer pays the owner's policy. The convention in Virginia, Maryland and West Virginia. Not reliable in Florida, where it varies by county. I could not verify the DC custom.
- Giving one number instead of a band. Six lines are genuinely unknowable at listing. A point estimate claims precision the inputs do not have.
- Not dating it. Every input has its own expiry, and an undated sheet cannot be defended later.
Why the concession is not a price reduction
A $20,000 concession and a $20,000 price cut take the same money out of the seller's proceeds. They are not the same transaction, in four ways.
- The recorded price differs, so the comp your next seller relies on differs.
- Transfer tax is computed on consideration, so the concession preserves the higher tax base while the price cut lowers it. Near the DC line that is decisive.
- The concession is capped by the buyer's loan programme and the price cut is not. Fannie Mae allows 9 percent at or below 75 percent loan to value, 6 percent from there to 90 percent, and 3 percent above 90 percent on a principal residence. FHA caps interested party contributions at 6 percent of the sales price on a forward mortgage.
- Appraisers must report and adjust for concessions, and Fannie Mae says a strict dollar for dollar deduction is not appropriate.
Fannie Mae Selling Guide B3-4.1-02 on interested party contributions, updated 7 May 2025, and B4-1.3-09 on adjustments to comparable sales, updated 4 June 2025; HUD Handbook 4000.1 part II.A.4.d for the FHA forward mortgage limit. Read 16 September 2026.
A tenth is less an error than a framing gap. Staging, the pre listing inspection and pre listing repairs never reach a settlement statement, because they were paid months earlier. A sheet showing only settlement costs and calling the bottom line net overstates what the seller made.
How to present it without creating a problem
I went looking for the ethics rule on net sheets. There is not one. I searched the 2026 Code of Ethics for estimate, closing costs, net and proceeds, and no Article or Standard of Practice uses any of them. Worth saying plainly.
Four provisions do reach it.
| Provision | What it requires | How it bites on a net sheet |
|---|---|---|
| Article 1 | Protect and promote your client's interests | The sheet serves the seller's decision, not the listing |
| Standard of Practice 1-3 | Do not deliberately mislead the owner as to market value when securing a listing | The closest thing to a net sheet rule, and it is about value, not costs |
| Article 2 | Avoid exaggeration, misrepresentation or concealment of pertinent facts | The operative misrepresentation article |
| Article 11 and SOP 11-1 | Conform to the competence reasonably expected, unless the gap is disclosed in advance | Disclosure cures the gap, which is the model for your disclaimer |
NAR 2026 Code of Ethics and Standards of Practice, read 16 September 2026.
Standard of Practice 1-13 gets cited in net sheet discussions constantly. It does not apply. It governs buyer and tenant agreements: cooperation policies, negotiability of compensation, dual agency, the confidentiality of offers. A buyer side rule. If someone tells you your seller net sheet is governed by 1-13, they have not read it.
Give a band, and build it honestly
Vary only the lines that are genuinely unknown. The optimistic bound is no concession, no repair credit, compensation at the low end of what you see locally, and the earliest realistic closing. The conservative bound is a concession at the local norm, a repair allowance, compensation at the high end, and thirty more days of per diem.
Carry a contingency if you want one, but label it. An unlabelled cushion is a small misrepresentation: the seller cannot see it or challenge it. And it should cover what is structurally unknowable, not what you could have looked up. Padding the transfer tax because you did not check the rate is an error with a cushion on top. If the conversation that follows is about price rather than costs, work from the price reduction scripts instead.
What belongs on the face of the sheet
- The date prepared, and a version number if you revise it.
- The assumed closing date, because per diem and prorations both key off it.
- The payoff good through date, or a statement that the payoff is estimated and not ordered.
- The source of each figure: per payoff statement dated, per statutory rate, estimated not quoted.
- The jurisdiction assumed. Everything above exists because that matters.
I could find no required disclaimer language in any of the four jurisdictions I checked, and none in the Code. Use your brokerage's approved version. A defensible one says the figures are estimates rather than a guarantee, that no title search has been performed so unknown liens may exist, that rates are current as of the date prepared, that no tax advice is given, and that the settlement statement controls.
What this guide does not cover
Three neighbours to this topic, each with its own guide.
- What the house is worth. A net sheet takes price as an input. Getting it right is a different discipline, covered in how to do a CMA that wins the listing.
- The appointment the sheet sits inside. The structure is in the listing presentation template. The net sheet is one section of it, not the whole thing.
- Sellers who are their own agent. A FSBO asking you for a net sheet is a different conversation, handled in the FSBO conversion guide.
Every rate above is jurisdiction specific and several adjust on their own schedule. You have the four I am licensed in, from statute, and two states that break the pattern hard enough to prove the point. Not a fifty state table, because the honest version of that table is mostly the words varies by county. Use the structure here rather than the numbers.
Getting the sheet right does not win listings by itself. It removes the reason a seller hesitates, which is not knowing what they walk away with. If the harder problem is filling the calendar at all, that is what my real estate coaching program is for.
Frequently asked questions
What is a seller net sheet?
A seller net sheet is an estimate, usually prepared by the listing agent, of what a seller will receive after every cost of sale is deducted from the price. It typically covers brokerage compensation, transfer and recordation taxes, settlement and title charges, the mortgage payoff, association fees, prorated taxes and dues, and any concession to the buyer. Nothing on it binds anyone. The seller's controlling figures arrive on the settlement statement, and on a seller Closing Disclosure where the settlement agent prepares one. The buyer's Closing Disclosure is the borrower's document, and a cash sale produces none at all.
Who prepares a seller net sheet?
Usually the listing agent, before the property goes on the market and again when an offer arrives. Title and settlement companies also produce estimates of proceeds, which come from the party who will actually disburse. I could not find a state regulating agent-prepared net sheets by name, but state misrepresentation and disclosure rules can reach a careless one.
How is a net sheet different from a Closing Disclosure?
A Closing Disclosure is a federal form produced by the lender through the settlement agent under Regulation Z at 12 CFR sections 1026.19(f) and 1026.38, and it must reach the consumer at least three business days before consummation. A net sheet is an informal estimate with no prescribed content, no timing rule and no tolerance limits. An ALTA settlement statement is a third document, produced at closing, which ALTA says is not meant to replace the Closing Disclosure.
Should the mortgage payoff or the loan balance go on a net sheet?
The payoff, always. A payoff statement is the lender's binding figure through a stated date and includes interest accrued to that date, a payoff statement fee, a wire fee, the release recording fee, and anything the servicer has capitalised. On a $400,000 balance at 6.5 percent, per diem interest alone is about $71 a day, roughly $2,137 across a thirty day escrow. Under 12 CFR section 1026.36(c)(3) a servicer must provide an accurate payoff statement within a reasonable time and no more than seven business days after a written request, with exceptions including bankruptcy and foreclosure.
How does buyer-broker compensation appear on a net sheet after the NAR settlement?
It can appear either as broker compensation or as a seller concession, and the two are not interchangeable. Since 17 August 2024 offers of compensation may not be published on an MLS, written buyer agreements are required before touring, and the listing agent needs the seller's prior approval before an offer of compensation is made or paid. The seller nets the same either way, but a generic concession consumes the buyer's interested party contribution capacity, capped at 9, 6 or 3 percent by loan to value on a conventional principal residence, while compensation structured as such has generally sat outside those caps under April 2024 agency guidance. Confirm the current treatment with the buyer's lender.
What transfer taxes does a seller pay?
It depends entirely on jurisdiction. In Virginia the grantor tax is 0.10 percent of price, and the Northern Virginia localities add a WMATA capital fee and a congestion relief fee for a seller-side total of 0.30 percent. DC charges 1.1 percent, rising to 1.45 percent on the entire amount once consideration reaches $400,000. Maryland's state tax is 0.5 percent, customarily split, with county transfer taxes on top. West Virginia runs 0.33 to 0.55 percent.
Should a seller net sheet show one number or a range?
A range, with the midpoint shown inside it. At listing six lines are genuinely unknowable: the payoff until it is ordered, any draw on a home equity line, buyer-broker compensation, any concession, repair credits after inspection, and liens that only surface in the title search. A single number asserts a precision the inputs do not support, and it produces the you-told-me conversation at closing. Date the sheet and label any contingency you carry.
Saad Jamil is a Top 1% Realtor with Samson Properties in Chantilly, Virginia, licensed in Virginia, DC, Maryland and West Virginia since 2007, with more than $500 million in career sales and 900+ homes closed. He is not a lawyer, a CPA or a settlement agent. His transaction record is on his Zillow profile.
Rates and rules above are cited to statute, to the agency that publishes them, or to the underwriter practice guides that record local convention, with the date each was read. Conventions are labelled as conventions because they can be negotiated away in any contract. Several figures adjust on their own schedule and a few are set county by county, so quote your own jurisdiction rather than carrying these forward. This is educational content for licensees, not legal or tax advice.
Free: 5 Ways to Get More Listings Without Cold Calling
Five lead strategies that work without cold calls or ad spend, from an agent with $500M sold and 900+ homes closed.
No spam. Unsubscribe any time.
Your Coach